
Mortgage-holders navigating difficult times
Advertisement
Read this article for free:
or
Already have an account? Log in here »
We need your support!
Local journalism needs your support!
As we navigate through unprecedented times, our journalists are working harder than ever to bring you the latest local updates to keep you safe and informed.
Now, more than ever, we need your support.
Starting at $15.99 plus taxes every four weeks you can access your Brandon Sun online and full access to all content as it appears on our website.
Subscribe Nowor call circulation directly at (204) 727-0527.
Your pledge helps to ensure we provide the news that matters most to your community!
To continue reading, please subscribe:
Add Brandon Sun access to your Free Press subscription for only an additional
$1 for the first 4 weeks*
- Enjoy unlimited reading on brandonsun.com
- Read the Brandon Sun E-Edition, our digital replica newspaper
*Your next Free Press subscription payment will increase by $1.00 and you will be charged $20.95 plus GST for four weeks. After four weeks, your payment will increase to $24.95 plus GST every four weeks.
Read unlimited articles for free today:
or
Already have an account? Log in here »
Hey there, time traveller!
This article was published 26/10/2023 (1095 days ago), so information in it may no longer be current.
One in six mortgage-holders now find the financial aspects of their mortgages “very difficult,” the latest data from non-profit Angus Reid revealed. It added that this figure has doubled since March, despite the Bank of Canada having hiked rates only twice in that time span. What are the factors contributing to the difficulties facing mortgage-holders?
“The biggest contributor is rising interest rates. When financing or refinancing a property, the cost of borrowing today is resulting in higher payments and making the cost of living less affordable for most borrowers,” Munn Group Royal LePage Martin-Liberty Realty partner and realtor Zach Munn told the Sun.
Fusion Credit Union chief operating officer Leanne DeVliegere agrees with Munn that the common thread between the mortgage woes some are experiencing and broader economic indicators is the sharp rise in interest rates and the inflationary pressures the nation has experienced since early 2021.
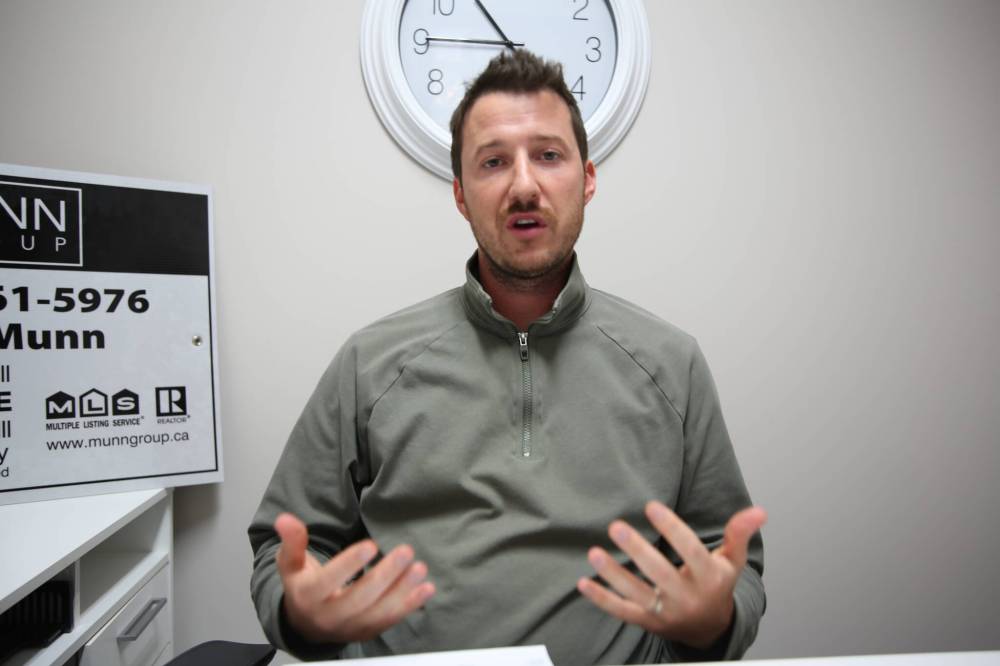
Munn Group Royal LePAGE Martin-Liberty Realty partner and realtor Zach Munn says low housing inventory in some areas is compounding the situation. (FILE)
“It becomes harder for the average household to make ends meet in this economic environment as each dollar earned holds less value than it once did,” she told the Sun.
Munn explained that a factor compounding the situation is low housing inventory, adding that due to the cost of construction, economic uncertainty, immigration and other economic factors, there’s not enough supply in certain areas, resulting in higher competition among buyers.
“People with adjustable-rate mortgages are experiencing these challenges the most. When you have a variable rate, and it goes from three per cent to seven per cent interest rates in about two years, the monthly payments will increase significantly,” Munn added. “Those who locked in at lower rates are better positioned until potentially their renewal. Also, those with higher mortgage amounts often feel mortgage rate increases more acutely than those with smaller mortgages.”
If you buy a home today and have a five per cent down payment versus a 25 per cent down payment, he explained, the interest cost is generally felt more as more of your monthly budget goes to mortgage payments.
“We see these trends aligning with the rising mortgage rates,” Angus Reid Institute research director Dave Korzinski said. “What is particularly notable is that those who are closer to their mortgage renewal are much more likely to express high levels of concern about what that will mean for their finances.”
Korzinski explained that the biggest economic context is that variable mortgage lending rates have been rising as the Bank of Canada’s overnight target rate has risen. To him, this is why the institute anticipates that those who hold a fixed rate are so worried, as their expectation is that the fixed rate will likely increase when they go to renew.
Westoba Credit Union chief executive officer Jim Rediger also noted that the increase in mortgage payments aligns with the Bank of Canada’s efforts to control inflation by raising interest rates.
“They were obviously trying to lower demand for goods and services by increasing interest rates over the last year and a half,” he told the Sun. “One of the unfortunate side effects of their inflation mandate to get it back down within their one to three per cent range is that borrowing costs become considerably higher. It’s part of trying to lower demand and dissuade people from borrowing money to buy things, which is all part of the demand.”
Rediger sees a combination of factors behind the challenge. To him, the pandemic caused a substantial spike in demand as people resumed their lives, creating an imbalance between the demand for goods and services and their supply.
“Many supply chains were disrupted by the pandemic and recovering from COVID led to labour shortages. This affected the supply of goods and services, further widening the gap. Additionally, the injection of money into the economy through pandemic programs has increased demand for goods and services,” Rediger said.

Westoba Credit Union chief executive officer Jim Rediger says early intervention is key for people struggling with mortgage payments, but budgeting is equally important. (Abiola Odutola/The Brandon Sun)
To Canadians struggling with mortgage payments, Rediger advised immediate communication with their lender.
“The sooner we can deal with the challenges that you’re having with mortgage payments, the more likely we can come up with solutions to help you manage your way through this, perhaps the next few months or maybe the next year with higher interest rates,” he said.
He explained that early intervention is key, but budgeting is equally important. “The challenge is always making ends meet,” Rediger said, recommending seeking help with household budgeting to find ways to reduce costs.
DeVliegere also echoed the importance of seeking advice from financial institutions and reviewing budgets to reduce costs. “Structuring debt obligations to minimize interest costs and payments can alleviate financial stress,” she said.
“It’s essential to budget carefully, cutting out as many non-essentials as possible. Paying down loans or credit card debt can make things more manageable in tough times,” Munn said. “When you can manage, save up a three-to-six-month-plus emergency fund. You can downsize, explore government assistance, rent, or find roommates, among other options if keeping up with payments is unsustainable.”
» aodutola@brandonsun.com
» X: @AbiolaOdutola